The outsourced chief investment officer (OCIO) model continues to expand in its adoption and complexity. Nearly $2 trillion in assets are under OCIO management and is expected to grow significantly. There are many reasons it can make sense to outsource your chief investment officer (CIO) functions and duties, but finding the right OCIO manager is not an easy task. This is why it’s expected—and highly recommended—to partner with an OCIO search consultant who can guide both the Board of Directors and the Investment Committee through the selection process. Learn more about the key qualities of an OCIO search consultant and how your organization can benefit from a well-vetted consultant.
Creating an Effective Investment Policy Statement
Retirement plan sponsors aren’t required to have an Investment Policy Statement (IPS) for their plan. However, having a written statement in place can facilitate your organization’s plan meeting federal and state regulations and fulfilling the fiduciary duties of a plan sponsor and/or their committee. However, not all policy statements are created equal, and there are a few topics every IPS should cover. Learn about what should be included in an effective Investment Policy Statement and how a well-crafted IPS can lighten the load of a committee that’s tasked with difficult plan decisions.
403(b) Sales Practices in Question
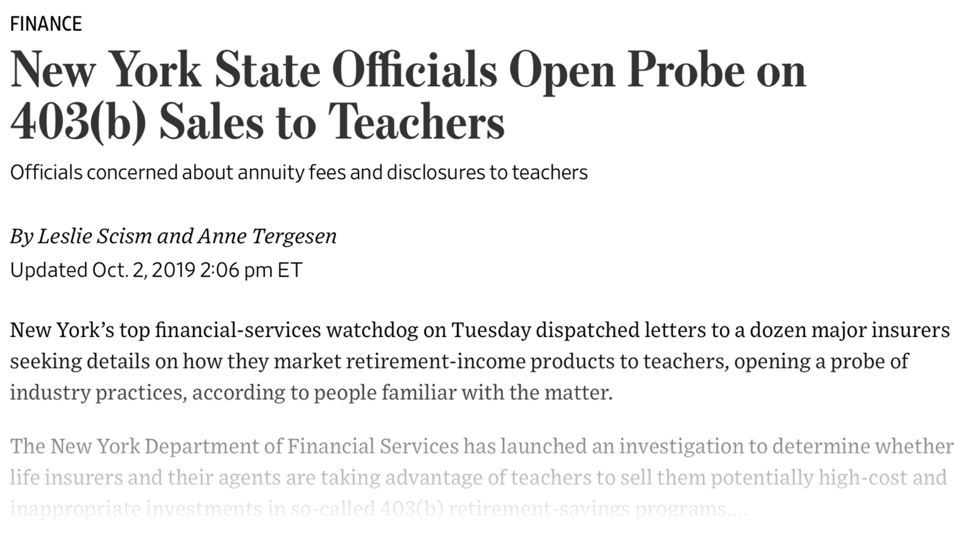
Over the past few months, we have seen several news stories that raised concerns about insurance companies and their retirement plan sales practices. For example, here is an article that was published in late 2019 by The Wall Street Journal:

Based on the investigations that have reportedly been launched by the New York Department of Financial Services, as well as the Securities and Exchange Commission (SEC), how should retirement plan sponsors respond?
Are You a Fiduciary?
Administering a retirement plan and managing its assets requires certain actions and involves specific fiduciary responsibilities. If you make decisions that impact your organization’s retirement plan, you’re likely considered a fiduciary under the Employee Retirement Income Security Act of 1974 (ERISA). With the current scrutiny over retirement plan litigation, it is imperative that plan fiduciaries understand their responsibilities and adhere to ERISA’s standards. Learn more about who is considered a fiduciary, their fiduciary responsibilities, and how to fulfill their responsibilities to their participants.
A Closer Look at Funds and Fees
Meeting Your Fiduciary Responsibilities
Managing a 403(b) plan isn’t easy. Since 2006, the Department of Labor’s regulation of 403(b) plans has become increasingly complex and time consuming. Recent regulations, in effect since 2012, are the fee disclosure regulations, which require schools to determine if the fees paid to investment managers and retirement plan service providers are “reasonable.” Unfortunately, the Department of Labor did not create a template or checklist for plan sponsors, so this interpretation is sometimes challenging.
- « Previous Page
- 1
- 2
- 3
- 4
- 5
- …
- 22
- Next Page »